
Net Worth Calculator: What You Own, and What Would Go Through Probate
Your net worth is everything you own minus everything you owe. Add up the assets, subtract the debts, and the difference is the number.
This calculator does that in about two minutes. Then it does the part every other one skips: it sorts your assets by how each one is held, so you can see which would pass straight to the person you named and which would sit in probate first. Same list, one extra column, a very different answer.
Nothing is saved and nothing is sent anywhere. The numbers stay in your browser.
Calculate your net worth
Round numbers are fine. The ownership column is the one that changes the answer, so give it a moment.
Net worth
Enter a few amounts to see the totals.
Of everything you own, before debts
- Passes directly to the person named 0%
- Goes through probate 0%
- Still to check 0%
What lands in probate
- Nothing yet. Fill in some amounts above.
What decides this is how each thing is held, not what it is worth. Anything joint with right of survivorship, anything with a named beneficiary and anything already in a trust goes straight to the person named on the paperwork. Whatever is left in one name alone is what a court has to move. Not sure stays in its own line rather than being guessed either way.
This hypothetical example is used for illustrative purposes only. Actual results will vary.
This information is not intended as tax, legal, investment, or retirement advice or recommendations, and it may not be relied on for the purpose of avoiding any federal tax penalties. You are encouraged to seek guidance from an independent tax or legal professional. The content is derived from sources believed to be accurate.
How an asset passes depends on how it is titled and on the rules of the state where the estate is settled. The split shown above follows the general rule and does not account for state specifics.
Four numbers, and what each one is telling you
Net worth
Assets minus debts. It is a snapshot of one day, and it moves with the housing market and with every loan payment. Read it as a trend against your own last year, not as a scoreboard against anyone else.
Passes directly
Anything held jointly with right of survivorship, anything with a named beneficiary, and anything already titled to a trust. These reach the named person without a judge and usually without a wait.
Goes through probate
Whatever is left in your name alone. A court confirms the will, appoints someone to act, and supervises the handover. It takes months, it costs money, and the file is public. This is the number a plan is built to shrink.
Still to check
Anything you marked not sure. It is kept in its own line rather than guessed, because a guess in either direction gives you a number you cannot act on. Each of these is one phone call or one login away from a real answer.
How to calculate net worth
The formula has two halves and no tricks.
Assets are everything you own that has a market value today:
- the home, and any other property or land
- checking and savings balances
- investment accounts and retirement accounts
- the payout of a life insurance policy
- vehicles
- a share in a business
- the contents of the house, taken together
Use what each one would sell for now. Not what you paid for it, and not what you hope it becomes.
Debts are the balances you would still owe tomorrow: the mortgage, car and student loans, card balances, and anything else financed.
Subtract the second total from the first. That is your net worth. It can be negative early in a working life without meaning anything has gone wrong, and it moves every month whether you look at it or not.
Which assets skip probate, and which do not
Size is not what decides this. Ownership is.
Three arrangements hand an asset to a named person without a court:
- Joint ownership with right of survivorship. The surviving owner simply keeps it.
- A named beneficiary, or a transfer-on-death registration. Retirement accounts and life insurance work this way by design, and many bank and brokerage accounts can be set up the same way.
- Assets already titled to a trust. The trust owns them, so nothing has to change hands at all.
Everything held in one name alone goes the other way, and that is what the red line in the calculator counts.
Two households with the same net worth can leave very different work behind. The difference is usually one line on a deed, or one beneficiary field somebody left blank fifteen years ago.
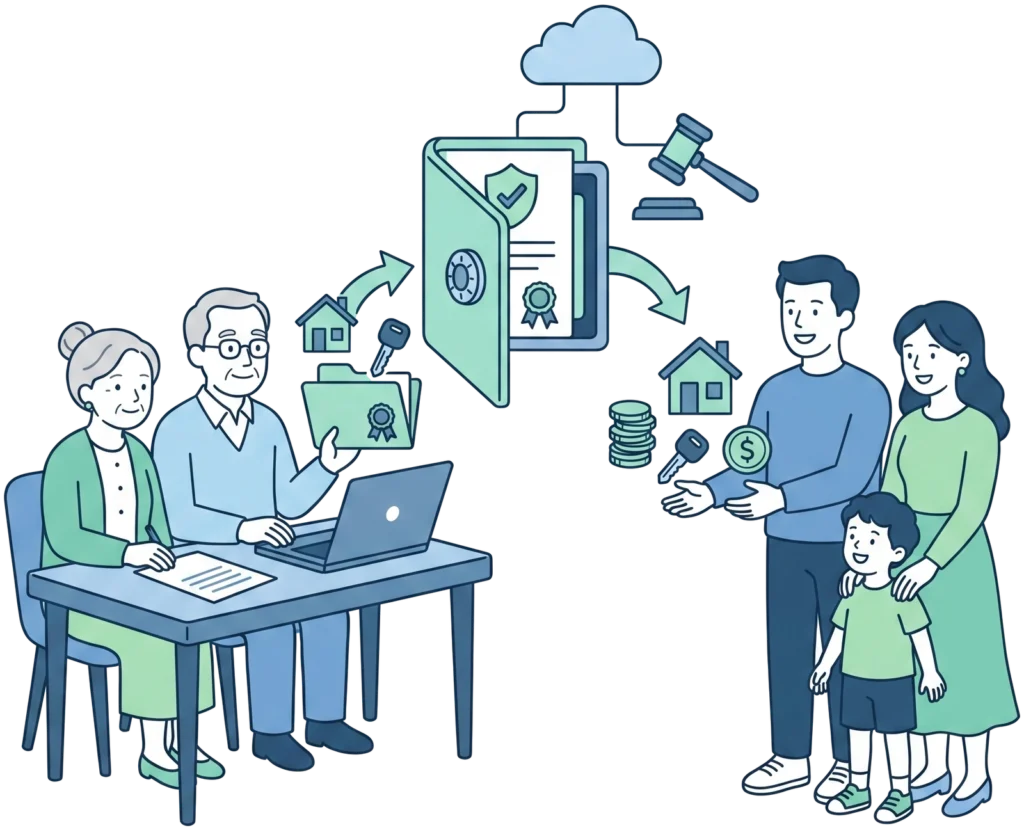
You have just written the first draft of a Schedule of Assets
Every trust needs one. It is the inventory of what the trust holds, and it is the step people put off, because starting from an empty page is unpleasant.
You did not start from an empty page. The list you just filled in is the same list, in roughly the same order. If you decide to go further, it carries over.
Questions people ask before they start
How do you calculate net worth?
Add the market value of everything you own, add up every balance you still owe, and subtract the second from the first. Nothing else belongs in the formula.
Should I include my house?
Yes, at what it would sell for today, with the remaining mortgage on the other side. Counting one without the other is the most common way people end up with a figure that flatters or frightens them for no reason.
Do retirement accounts count?
They count as assets, at the current balance. They also carry a named beneficiary, which is why they usually land on the line that skips probate. Worth confirming rather than assuming, because the name on that form is often years out of date.
What is a good net worth?
No single figure answers that. It depends on age, income, where you live and what you are saving toward. The comparison that tells you something is against your own figure a year ago.
How often should I redo this?
Once a year is plenty for the total. The ownership column deserves a look sooner, after anything that changes who owns what: a house, a new account, a marriage, a divorce, a birth, a death in the family.